International health insurance for Irish digital nomads
Your home cover does not follow you abroad
The EHIC covers necessary public care on short stays in the EU, EEA and Switzerland. Never private treatment, never repatriation, nothing beyond Europe. Irish nomads living abroad need international health insurance.
Travel vs health once you leave
A domestic plan does not become travel insurance, and travel insurance does not become international health cover.
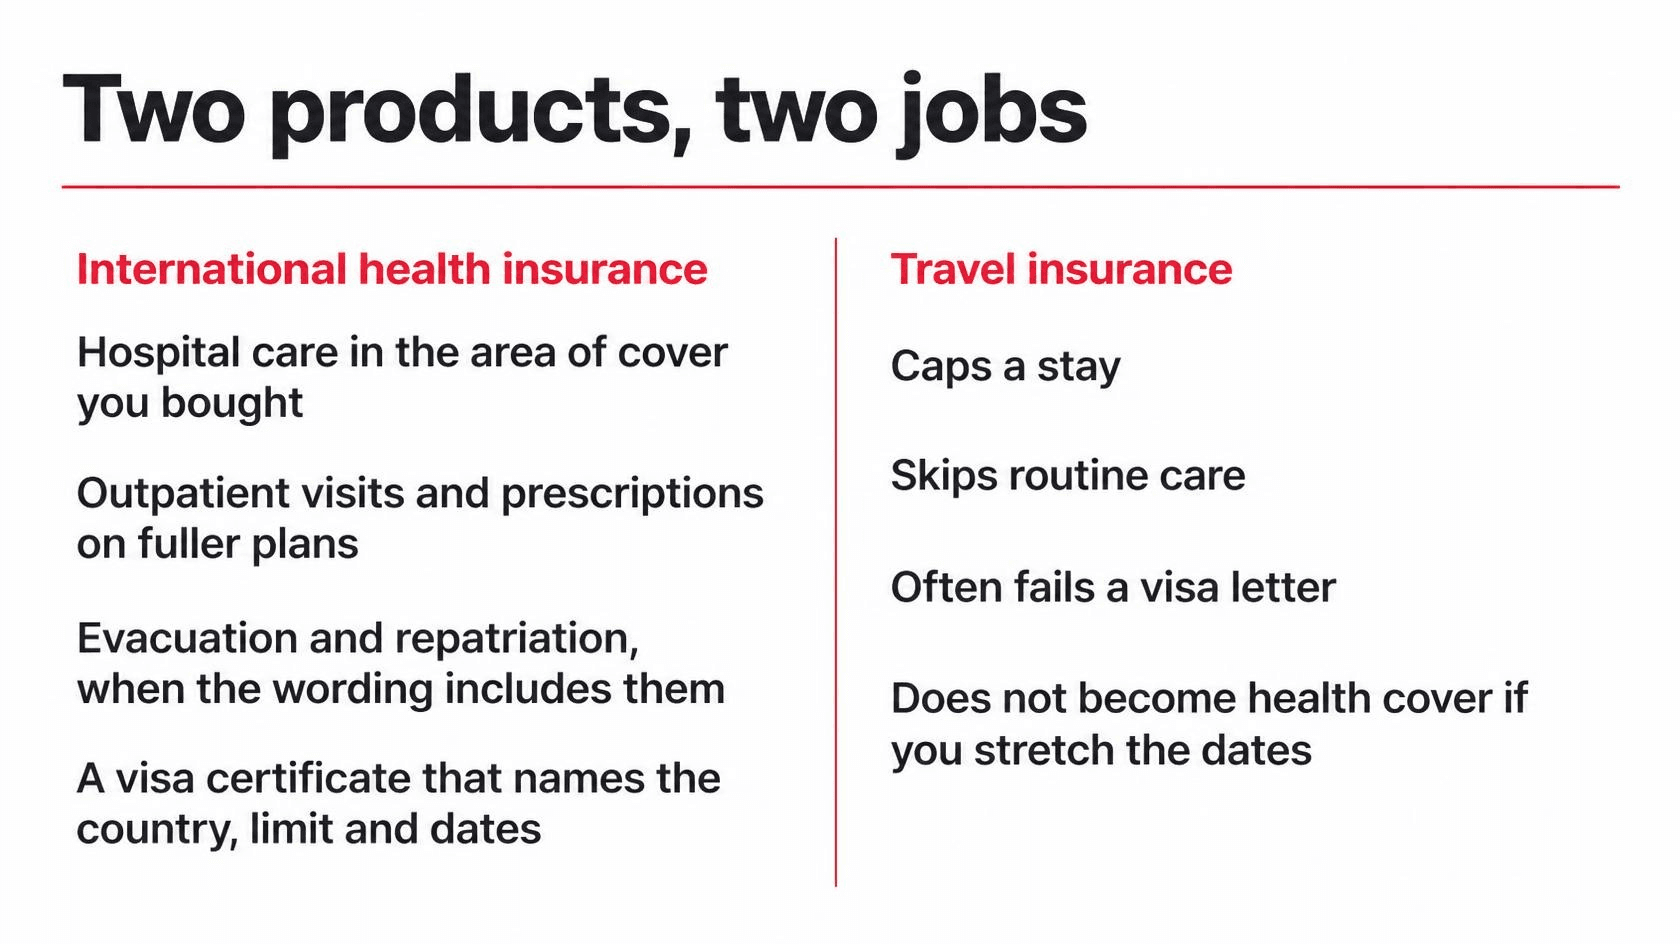
The difference is set out in our guide to when travel insurance stops and nomad health insurance starts. Use the table, then the essay below.
Travel insurance versus nomad-style cover versus international health insurance
Duration
- Travel
- Trip that ends; often 30–90 days per stay
- Nomad-style
- Continuous, renews while you are away
- International health
- Annual, portable across countries
Routine care
- Travel
- No
- Nomad-style
- Rarely
- International health
- Yes, if outpatient is in the plan
Pre-existing
- Travel
- Usually excluded
- Nomad-style
- Usually excluded
- International health
- Underwritten
Home country
- Travel
- Stops when you land
- Nomad-style
- Usually excluded
- International health
- Optional region
Visa-ready
- Travel
- Often rejected
- Nomad-style
- Sometimes
- International health
- Usually, unless a local insurer is required
Evacuation
- Travel
- If listed
- Nomad-style
- Usually
- International health
- Should be included
| Attribute | Travel | Nomad-style | International health |
|---|---|---|---|
| Duration | Trip that ends; often 30–90 days per stay | Continuous, renews while you are away | Annual, portable across countries |
| Routine care | No | Rarely | Yes, if outpatient is in the plan |
| Pre-existing | Usually excluded | Usually excluded | Underwritten |
| Home country | Stops when you land | Usually excluded | Optional region |
| Visa-ready | Often rejected | Sometimes | Usually, unless a local insurer is required |
| Evacuation | If listed | Usually | Should be included |
How long your home cover lasts abroad
Only inside the EU, EEA and Switzerland, and only for short stays.
The EHIC covers medically necessary public healthcare during a temporary stay of under three months, and it is tied to being ordinarily resident in Ireland, so once you move abroad long term you generally lose eligibility too. Outside Europe it gives nothing.
What breaks when you leave
The EHIC covers public care only, never private treatment, and patient charges can still apply even inside Europe.
It does not cover medical repatriation or the cost of flying home, and it gives no cover at all outside the EU/EEA and Switzerland. The Irish State will not step in either: the Department of Foreign Affairs says it cannot pay your medical bills, an evacuation, or repatriation.
What you need instead
For trips, comprehensive travel insurance bought before you go, covering overseas medical treatment and, critically, medical repatriation and evacuation, the items the EHIC and the State never pay.
Insurance Ireland recommends at least €1 million of medical cover. For living abroad long term, an international health plan rather than a short-stay travel policy, since the EHIC is for temporary stays and Irish public entitlement is residence-based. Check it covers pre-existing conditions and the countries you will actually be in.
Common mistakes
- Treating the EHIC as travel insurance; the government is explicit it is not a substitute
- Assuming the EHIC works outside Europe; it covers nothing outside the EU/EEA and Switzerland
- Expecting the EHIC to cover private care; it is public-system only, and charges can still apply
- Expecting repatriation or the flight home to be covered; the EHIC never pays it
- Assuming you keep EHIC eligibility once you move abroad; it is tied to ordinary residence in Ireland
- Relying on the State to help; the Department of Foreign Affairs will not pay medical bills, evacuation or repatriation
- Confusing the Irish EHIC with the UK's GHIC; only Northern Ireland residents use the GHIC
How Irish cover really treats a leaver
Ireland's EHIC covers only public healthcare on short stays inside the EU/EEA and Switzerland, never private care or repatriation, and nothing outside Europe; the Department of Foreign Affairs notes a medical evacuation to Ireland from India can cost up to €145,000, which neither the EHIC nor the State will pay.
Ireland's public health entitlement runs on ordinary residence, not on what you have paid in.
The test the HSE applies is that you have been living in Ireland for at least a year, or that you intend to live here for at least a year. Citizens Information is explicit that entitlement is not based on tax payments or social insurance (PRSI) contributions. So it is a residence-and-intention test, not a membership you build up and then keep.
That framing decides what happens when you leave. Because the entitlement depends on actually living in Ireland or genuinely intending to, emigrating removes the basis for it. You do not keep Irish public cover the way you might keep a paid-up policy. Once Ireland is no longer where you live, you stop meeting the ordinarily-resident test, and there is no contribution record sitting in reserve for you to draw on later.
The European Health Insurance Card (EHIC) is often mistaken for a solution here, and it is not. The Irish EHIC is issued to people ordinarily resident in Ireland, and it covers only necessary healthcare during a temporary stay of up to three months in any EU or EEA country and Switzerland. It explicitly does not cover ongoing or permanent healthcare, and it does not cover treatment you go abroad specifically to receive. Citizens Information also states plainly that it is not an alternative to travel insurance.
For a nomad this cuts two ways. First, the EHIC exists only because you are resident in Ireland. Once you move abroad you are no longer ordinarily resident, so the Irish card stops being the right one, and the country you settle in becomes responsible for your cover. Inside the EU or EEA you would register there and, if eligible, hold that country's EHIC instead. Second, the EHIC does nothing outside the EU, EEA and Switzerland, so anywhere in Asia, the Americas or beyond it is worthless, and even within Europe it is short-stay, necessary-care cover, never cover for living somewhere.
Coming back is comparatively clean, because there is no contribution record to rebuild and no penalty for having been away. You regain access by satisfying the HSE that you are ordinarily resident again, meaning you are living in Ireland or intend to for at least a year, backed by documentary evidence such as a tenancy agreement or utility bills. In practice you can qualify from the point you return with genuine intent to stay, rather than serving out a fixed qualifying period.
It is also worth being honest about what the public system gives you even when you do qualify, because the free-healthcare picture people carry is only partly true. Full cover, meaning free GP visits, subsidised prescriptions and free public hospital care, comes with a medical card, which is means-tested on income. A GP visit card is a lesser thing: it covers GP consultations only, not hospital charges or drugs. Without either card, and most working-age people have neither, you pay the GP yourself, commonly somewhere around 50 to 65 euros a visit. One real improvement is that since April 2023 public hospital in-patient and day-case charges were abolished for everyone, so a public hospital stay itself is now free regardless of card status. But the everyday primary care a nomad is most likely to use is not automatically free.
Two Irish-specific things are easy to over-rely on. The Common Travel Area gives Irish and British citizens reciprocal rights that include access to healthcare in each other's country, so an Irish resident visiting the UK can get needs-arising, necessary care, and someone who actually moves to the UK joins the NHS there as a resident. It is a visit-and-necessary-care arrangement, not portable cover for planned treatment. And the domestic supports do not cross a border at all. The Drugs Payment Scheme, which caps a household's approved monthly medicine bill at 80 euros, and the Long-Term Illness Scheme, which gives free medicines for a fixed list of conditions such as diabetes, epilepsy and multiple sclerosis, both require you to be ordinarily resident in Ireland and only work through Irish pharmacies.
If you hold Irish private health insurance, understand community rating before you drop it to travel. Irish insurers must charge the same base premium regardless of your age or health, but Lifetime Community Rating adds a loading when you first take out cover later in life: 2% of the premium for each year you are aged over 34 without insurance, up to a maximum of 70%. There is relief for emigrants, but it is conditional and date-bound. If you were living in Ireland on 1 May 2015 and moved abroad on or after 1 November 2018, the Health Insurance Authority credits the time you spent abroad and you avoid the loading for that period, but only if you buy cover within nine months of returning to Ireland. Miss that nine-month window and years spent away can convert into a lasting premium loading once you rejoin.
Our take
For Irish nomads the EHIC is a Europe-only, public-only convenience, not a safety net.
The moment you leave the EU, or need a private hospital, or need flying home, it stops, and those are exactly the situations that bankrupt people.
Carry travel cover with evacuation for trips and an international plan once you actually live abroad. The number that should drive the decision is repatriation: the State puts a medevac from India at up to €145,000, and no EHIC will ever pay it.
FAQ
No. The EHIC gives no cover outside the EU/EEA and Switzerland, so in places like Thailand or the US you are fully self-pay. You need private travel or international health insurance.
No, and the government says so explicitly. It covers public care only, not private treatment, and never medical repatriation or the flight home.
No. The Department of Foreign Affairs is clear it cannot pay your medical bills, an evacuation or repatriation, which from India alone can cost up to €145,000.
Generally no. Eligibility is tied to being ordinarily resident in Ireland, with only narrow exceptions (such as Irish pensioners living in the EU, or posted and frontier workers).
Ireland issues the EHIC, administered by the HSE. Only Northern Ireland residents move to the UK-issued GHIC.
This page is the origin-country gap. It is not a passport ranking and it does not quote a premium. How we measure cost.
Find cover that actually follows you
The form asks about health and the visa. You get one offer by email. You pay the standard premium.
Get a quoteTypical destinations from here: Portugal, Spain, Netherlands, Thailand and Mexico. The entry rule that actually asks for cover is the D8 Digital Nomad Residence Visa and the Digital Nomad Visa (Visado para teletrabajadores de carácter internacional). Which product fits is the insurance choice, and whether you clear a threshold is the which nomad visa check.
Get a quote in 3 steps
- 01
Fill out
The form only asks what changes the plan.
- 02
Get a quote
We compare the panel against your route, stay and visa.
- 03
Decide on the offer
If it fits, you take the policy out with the insurer. We are not the insurer.
Have a look if this page was not the question you came with.