Destination
Healthcare in United Arab Emirates, and what it costs without cover
UAE healthcare is genuinely excellent and genuinely expensive. The real question for nomads isn't quality, it's stacking a mandatory local plan against international cover for evacuation and treatment outside the UAE without paying twice for the same thing.
A short trip to United Arab Emirates can still use travel cover. Living there needs international health insurance that outlasts the visa.
- Best for Long-term nomads
- Best for Remote employees
- Best for Families
- Best for Freelancers
- Insurance required?
- Requiredmandatory in UAE
- Recommended coverage
- $500,000+care is costly
- Emergency number
- 999 police998 ambulance
- Healthcare quality
- Private: world-class, costly
Your plan for United Arab Emirates
Plan your stay with the information below. Request a quote whenever you are ready.
1. Your stay
2. Visa requirements
Find out which entry and insurance rules apply to your stay.
Find visa information for my stay3. Healthcare costs
See what medical care could cost without insurance.
Explore costs in United Arab Emirates
You can request a quote at any time.
Nomadsurance is an independent matching platform, not an insurer. We help you find international health cover for your stay.
Get a quoteSaved in this browser when available. Your checklist records what you have reviewed; it does not confirm visa approval or insurance cover.
The system
Healthcare system in United Arab Emirates
The UAE operates a federal-plus-emirate model.
The Ministry of Health and Prevention (MOHAP) sets federal policy, while Dubai Health Authority (DHA) and the Department of Health Abu Dhabi (DOH) run their own regulatory and insurance schemes within the two largest emirates. Sharjah, Ajman, and the northern emirates largely follow MOHAP-led federal arrangements. The practical effect for nomads: rules around mandatory insurance, claim handling, and provider networks vary depending on which emirate you're resident in.
World-class private sector
The private sector is world-class and dominant for anyone with insurance. The major networks expat nomads will actually use include Mediclinic Middle East, NMC Healthcare, Aster, American Hospital Dubai, and at the top end Cleveland Clinic Abu Dhabi, a US-standard facility run as an extension of Cleveland Clinic's main brand. King's College Hospital London also operates in the UAE. Standards at these facilities are comparable to leading Western European or US private hospitals, with English ubiquitous, multilingual staff routine, and waiting times short by international standards.
Mandatory insurance
Mandatory insurance defines the market. In Dubai, the DHA requires all residents to hold valid health insurance meeting Essential Benefits Plan (EBP) minimum standards or higher. The lowest compliant local tier typically starts around AED 600 to 700 per year, though that plan only covers basic care on a narrow public-leaning network. In Abu Dhabi, the equivalent rules are administered by DOH, with the national health insurer operating the basic plan for low-income workers and a substantial commercial book on top. Renewing your residency visa requires showing a valid policy. Sponsoring family members requires you to cover them too.
Costs are international-tier, among the highest in the world for private care. A GP visit at an American Hospital Dubai-style facility runs into multiples of what you'd pay in most European markets. Inpatient stays at top-tier hospitals can rival US pricing, particularly for surgery, maternity, and oncology. This is exactly why mandatory insurance exists: the UAE government does not want uninsured residents at private hospital doors generating bad debt.
English is universal in healthcare. Arabic, Hindi, Urdu, Tagalog, and Russian-speaking practitioners are common across the major networks, reflecting the country's expat demographics. Mental health services have expanded significantly and are now broadly accessible in Dubai and Abu Dhabi, though stigma and reporting concerns are worth being aware of culturally.
What you'd pay
Typical costs
| GP visit (private clinic, expat-friendly) | AED 200 to 500 (~$55–135) |
|---|---|
| Specialist consultation | AED 400 to 900 (~$110–250) |
| Basic emergency room visit (non-admission, private) | AED 800 to 2,500 (~$220–680) |
| One-night hospital stay (private, Mediclinic / American Hospital / Cleveland Clinic Abu Dhabi tier) | AED 1,500 to 5,000 (~$410–1,400) |
| Common procedure (e.g. appendectomy, private) | AED 25,000 to 60,000 (~$6,800–16,000) |
| International health insurance from-price (32-year-old) | from around $100 to $180/month |
These are rough ranges. Real bills depend on the emirate (Dubai and Abu Dhabi sit at the top), hospital tier (Cleveland Clinic Abu Dhabi and American Hospital Dubai are well above network average), and whether you're using a DHA/DOH-mandated basic plan or full international cover. Out-of-pocket pricing for anyone uninsured is punitive by design.
Entry & stay
Visa, residency & insurance
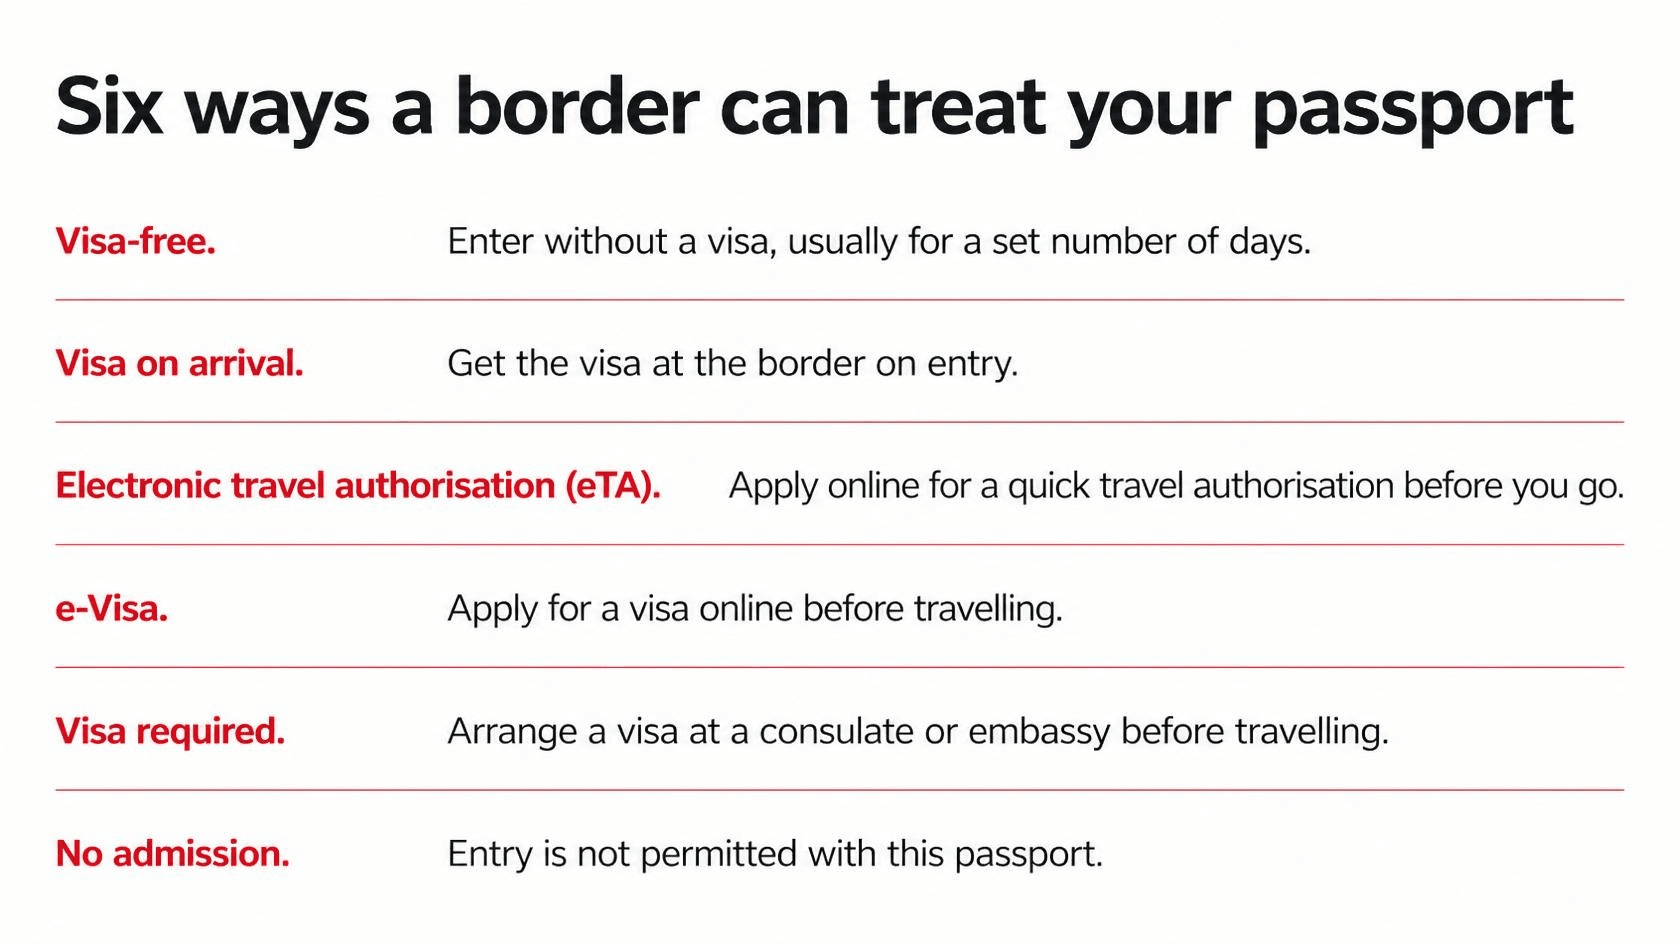
The UAE has built one of the most actively marketed residency stacks in the world for remote workers and high earners.
Tourist visas of 30 to 90 days are available for most nationalities, often visa-on-arrival. The Virtual Working Programme (UAE Remote Work Visa) is a one-year residency for remote employees of foreign companies meeting a monthly income threshold of around $3,500. The Golden Visa offers 5- or 10-year residency for investors, specialists, entrepreneurs, and high earners. The Green Visa is a 5-year self-sponsored residency for skilled professionals and freelancers. Freelance permits via free zones (DMCC, IFZA, Dubai Internet City, Ajman Free Zone among others) are the route most independent nomads actually take.
Insurance enforced at renewal
Every one of these routes except the short-stay tourist visa requires valid health insurance. This is enforced at issuance and again at renewal. You cannot collect your Emirates ID, the foundational residency document, without proof of cover. For Golden Visa and family sponsorship, the bar is higher and the renewal cycle longer, but the requirement is the same.
Does your international plan satisfy the mandate
The practical question for nomads is whether your existing international plan satisfies the local mandate. Sometimes yes: some international plans issue UAE-compliance certificates that meet DHA or DOH minimums. Often no, particularly with thinner or younger nomad-focused plans, the local regulator may require you to pair the international plan with a basic compliant local product. Always confirm in writing before you assume coverage.
Free zones add a wrinkle. Some bundle a basic local insurance product into the freelance permit package; others leave it to you. Read the package before signing.
Named floors, local-insurer rules, and the programmes that ask for nothing are in which visas require insurance.
Who these rules apply to: Applies to non-UAE / non-GCC nationals. ~80+ nationalities (US, UK, EU, Canada, Australia, Japan) get a visa on arrival; others need a pre-arranged e-visa or a sponsor.
- Recommended
Tourist / business visa (visa on arrival / e-visa)
Visa on arrival 30 or 90 days; tourist e-visa 60 days, extendable once to ~120 daysShort visits, tourism and business meetings. Passport valid 6+ months; visa-on-arrival eligibility or an approved e-visa
- Required
Work (employment) residence visa
Typically 2 years, renewableForeign nationals with a UAE job offer. Employment contract + MOHRE work permit; employer-sponsored, plus medical test
- Required
Student residence visa
1 year (some up to 2), renewable for the study periodInternational students at a UAE-licensed institution. Acceptance letter from an accredited institution; university-sponsored
- Required
Remote work (digital nomad) visa
1-year residence permit, renewableMost nomadsRemote professionals employed by or owning a company outside the UAE. Income of at least US$3,500/month (proven over 6 consecutive months); valid contract or company ownership
- Required
Golden visa (long-term residence)
5 or 10 years, renewable; self-sponsored (no employer needed)Investors, entrepreneurs, specialised talent and top students. A qualifying category, e.g. property investment (Dubai rules eased in 2026), AED 2M investment, or recognised talent
- Required
Green visa (skilled / self-sponsored residence)
5 years, renewable; self-sponsoredSkilled employees, freelancers and smaller investors. By category, e.g. freelancers need a UAE freelance permit and income above ~AED 360,000/year
- Required
Retirement residence visa
5 years, renewable while conditions are metForeign nationals aged 55+. Age 55+ with property ≥ AED 1M plus savings ≥ AED 1M, or annual income ≥ AED 180,000
Valid UAE health insurance is mandatory nationwide for all residence and work visas since 1 Jan 2025. A reported 2026 rise of the remote-work income floor to US$5,000 (and higher insurance cover) could not be confirmed against an official source. The verifiable figure is US$3,500/month; confirm with ICP/GDRFA (u.ae).
Once a stay outruns a travel policy's trip limit, our guide to travel insurance vs nomad health insurance explains which kind of cover fits.
Tick this when you have finished reviewing. You can change it at any time.
Next: explore healthcare costsInteractive
Verified pricesWhat would it cost in the UAE without insurance?
Off a kerb, off a bouldering wall, off a wet bathroom floor. No admission, just a bad afternoon.
| Emergency room, on arrival | $135–$545 |
| X-ray to confirm the break | $41 |
| You pay, out of pocket | $176–$586 |
That is the bill if you pay it yourself. Get a quote to see what would actually respond.
Get a quoteTypical private-care estimates for illustration, not a quote. Actual bills vary by hospital, city and severity.
Tick this when you have finished reviewing. You can change it at any time.
Get a quoteLocal risk notes
What to watch out for in United Arab Emirates
- Mandatory local does not equal international cover for travel outside the UAE.
- A DHA-compliant local plan is excellent inside Dubai and largely useless when you're in Bali. Most established nomads stack a local plan with an international plan rather than choosing one.
- Alcohol-related exclusions. Many UAE-issued plans contain alcohol-related exclusion clauses on ER and inpatient claims that are broader than international norms. Read these specifically.
- Dental and maternity rules. The UAE has specific minimum maternity coverage requirements for residents that vary by emirate, and dental is often a separate rider rather than included.
- Summer extreme-heat claims. Heat-stroke and heat-exhaustion ER visits have nuances around outdoor work, pre-existing conditions, and recreational activity that some plans handle inconsistently.
- Sharia-compliant (Takaful) plans. These exist and meet local mandates, with specific exclusions around certain treatments. Fine if you understand the structure; surprising if you don't.
- Visa renewal timing. Insurance must be valid at the moment of renewal. Gap days between an expiring international plan and a new local one have stopped Emirates ID renewals. Plan the overlap deliberately.
Common questions
United Arab Emirates insurance FAQ
Sometimes, not always. Some international plans issue UAE-compliance certificates that meet DHA or DOH minimums on certain tiers. Many nomad-friendly plans do not. The safest pattern is to pair your international plan with a basic DHA/DOH-compliant local product to satisfy the mandate, and use the international plan for everything that actually matters.
The DHA mandate applies to all Dubai residents regardless of whether your visa is sponsored by a mainland company or a free zone. What differs is whether the free zone bundles a basic compliant plan into your permit. DMCC and IFZA structures vary, so read the package before assuming anything.
Dubai is regulated by DHA with the Essential Benefits Plan framework. Abu Dhabi is regulated by DOH with the national health insurer playing a central role. Minimum coverage structures, claim handling, and approved insurer lists differ. If you split time between the two emirates, your plan needs to work across both networks.
Yes. Sponsors are responsible for covering dependents, and family residency visas won't issue or renew without proof of cover for each dependent. Family international plans handle this cleanly.
Network access depends on the specific plan and tier. A cashless prepaid-card plan's direct-billing network in the UAE covers most major private hospitals; a full IPMI plan typically reimburses or direct-bills depending on tier. Always confirm the exact hospital list before treatment.
It's operated as part of the Cleveland Clinic system with US-trained clinicians and similar protocols. Generally considered the top-tier facility in the UAE for cardiac, neurosurgery, and oncology. Expect pricing to match.
No. Health insurance with UAE validity is a documented requirement for the Virtual Working Programme. The certificate has to name the UAE explicitly in the country list.
Many UAE-issued plans have broader alcohol-related exclusions than international norms. International plans purchased outside the UAE typically follow standard exclusion language, but read the policy.
Substantially better than five years ago. Major networks now have psychiatry and psychology services. Cultural and reporting considerations exist, so talk to your insurer about confidentiality specifics if that matters to you.
Sometimes. Some free zones bundle a basic compliant plan; others leave it to you. Read the permit package and confirm with the free-zone authority before assuming.
At the top end (Cleveland Clinic Abu Dhabi, American Hospital Dubai), pricing is in the US private-hospital range. Across the broader private network it's typically below US pricing but well above European. The mandatory insurance structure is what makes it workable for residents.
For a true short stay, yes. For anything tied to a residency permit (Virtual Working Programme included) you'll need a plan that meets the local mandate, not generic travel cover.
This page is the healthcare guide. It does not quote a premium and does not name an insurer. How we measure cost.
Get a quote in 3 steps
- 01
Fill out
The form only asks what changes the plan.
- 02
Get a quote
We compare the panel against your route, stay and visa.
- 03
Decide on the offer
If it fits, you take the policy out with the insurer. We are not the insurer.
Have a look if this page was not the question you came with.