International health insurance for Canadian digital nomads
Your home cover does not follow you abroad
Canadian provincial plans reimburse a fraction of care abroad, never pay the hospital up front, and cover no evacuation. International health insurance is the product that follows you; travel cover only fits a trip that still ends.
Travel vs health once you leave
A domestic plan does not become travel insurance, and travel insurance does not become international health cover.
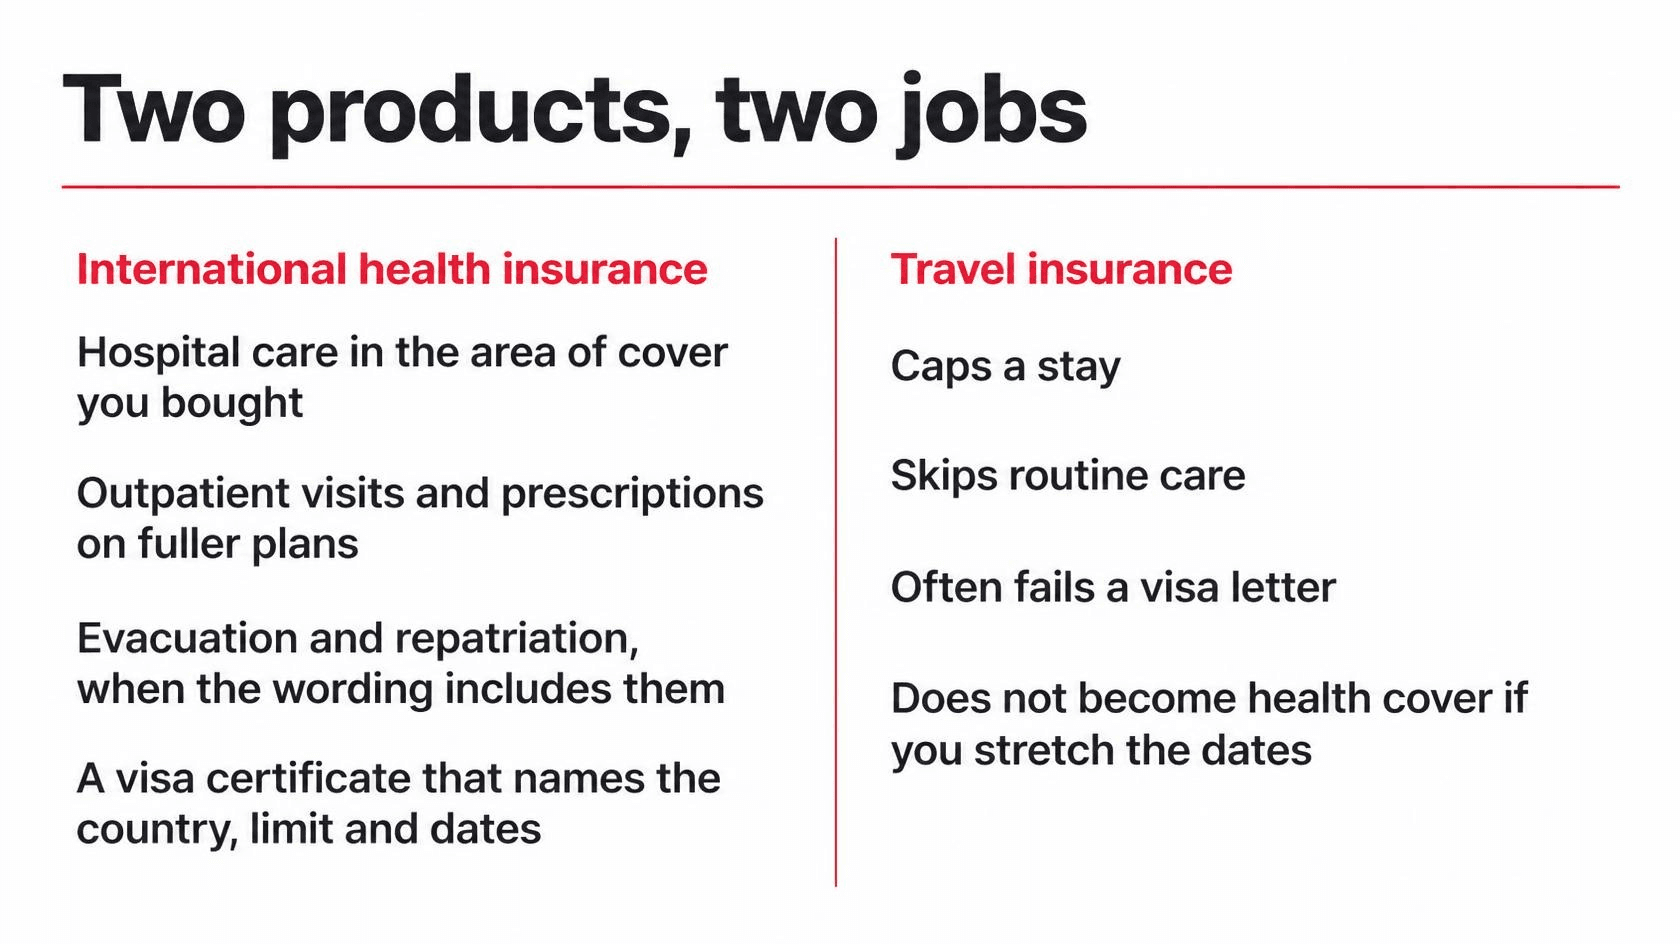
The difference is set out in our guide to nomad health insurance. Use the table, then the essay below.
Travel insurance versus nomad-style cover versus international health insurance
Duration
- Travel
- Trip that ends; often 30–90 days per stay
- Nomad-style
- Continuous, renews while you are away
- International health
- Annual, portable across countries
Routine care
- Travel
- No
- Nomad-style
- Rarely
- International health
- Yes, if outpatient is in the plan
Pre-existing
- Travel
- Usually excluded
- Nomad-style
- Usually excluded
- International health
- Underwritten
Home country
- Travel
- Stops when you land
- Nomad-style
- Usually excluded
- International health
- Optional region
Visa-ready
- Travel
- Often rejected
- Nomad-style
- Sometimes
- International health
- Usually, unless a local insurer is required
Evacuation
- Travel
- If listed
- Nomad-style
- Usually
- International health
- Should be included
| Attribute | Travel | Nomad-style | International health |
|---|---|---|---|
| Duration | Trip that ends; often 30–90 days per stay | Continuous, renews while you are away | Annual, portable across countries |
| Routine care | No | Rarely | Yes, if outpatient is in the plan |
| Pre-existing | Usually excluded | Usually excluded | Underwritten |
| Home country | Stops when you land | Usually excluded | Optional region |
| Visa-ready | Often rejected | Sometimes | Usually, unless a local insurer is required |
| Evacuation | If listed | Usually | Should be included |
How long your home cover lasts abroad
A small fraction, then nothing.
Provincial plans reimburse only tiny daily caps abroad (British Columbia about CA$75 a day, Quebec about CA$100 a day) and never pay up front. Each province also limits how long you can be away, roughly 212 days a year in Ontario and Alberta and 183 days in Quebec, before you lose coverage and must re-apply on return.
What breaks when you leave
The provincial plan pays only a few dollars a day against bills that run into the tens or hundreds of thousands, and you must pay the hospital yourself first and claim a partial refund later.
Medical evacuation and repatriation, which can exceed CA$50,000, are not covered by your province or by the Government of Canada. Non-emergency care abroad needs prior written approval, and private-facility care is often excluded outright.
What you need instead
For trips and snowbird stays, travel medical insurance bought before you leave, covering emergency treatment, evacuation, and repatriation, the items the province never pays.
For living abroad long term, an international health plan, since travel policies are trip-length and provincial coverage lapses once you stop being a resident. Confirm it covers your pre-existing conditions and read the stability-period clause.
Common mistakes
- Assuming your provincial card covers you abroad; it pays only a small fraction and never up front
- Expecting the Government of Canada to step in; it will not pay your medical bills or an evacuation
- Ignoring the pre-existing-condition stability clause; a small change can void the policy
- Travelling to a destination under a Government of Canada advisory, where insurers may refuse the claim
- Overstaying your province's absence limit and silently losing coverage
- Assuming non-emergency care abroad is covered; it needs prior written approval
- Buying nothing for short trips; BC advises cover even for a single day away
How Canadian cover really treats a leaver
Canadian provincial health plans reimburse only tiny daily caps abroad and never pay up front: Quebec's RAMQ gives the example of a three-day Florida hospital stay costing up to US$200,000, of which the plan reimburses about CA$300.
Canada has no single national plan you carry with you.
Health coverage is provincial, and each province ties it to being a resident who is physically present there for most of the year. Ontario runs OHIP, British Columbia runs MSP, Alberta runs AHCIP and Quebec runs RAMQ, and each has its own absence limit, so when your coverage lapses depends entirely on which province you left.
The physical-presence tests differ province by province. Ontario requires you to be in the province at least 153 days in each 12-month period and normally allows an absence of only up to about seven months in any 12 months, though a one-time longer trip of up to two years can be approved if Ontario stays your primary home. British Columbia requires you to be present at least six months per calendar year and allows up to seven months away for vacation. Alberta requires 183 days of presence per 12 months and allows an out-of-Canada absence of under six consecutive months, extendable with prior approval, up to 212 days for recurring vacation, up to 24 months for travel or study, and up to 48 months for work. Quebec lets you be absent no more than 183 days in a calendar year; go over and you lose eligibility for that whole year and can be billed back for services you used.
Prior approval is the trap. Most of the longer-absence allowances only hold if you notify the province, and usually get the extended absence approved, before you leave. Overstaying the limit without arranging it typically cancels coverage from the date you crossed the line, not from when you get around to telling them.
Even while valid, provincial plans pay little or nothing abroad. Ontario is the clearest example: for care outside Canada OHIP pays at most roughly 200 to 400 Canadian dollars per day for inpatient hospital care and about 50 dollars per day for outpatient emergency care, a small fraction of real foreign hospital bills. Other provinces are similar or have stopped paying for out-of-country care entirely. So even before your coverage technically lapses, it is not meaningful protection overseas.
The return is where Canada is harsh and unlike the UK. Most provinces make you serve a waiting period when you re-establish residency. British Columbia's wait is the balance of the month you arrive plus two more months. Quebec applies a waiting period of up to three months before RAMQ resumes. Ontario reinstates more quickly but still expects you to re-establish residency and meet its presence test. During that gap you have no provincial coverage and need private insurance to bridge it.
The pattern holds beyond the big four, with the exact numbers shifting again. Manitoba wants you present roughly 183 days a year and lets you keep coverage during a travel absence of up to seven months. Saskatchewan treats five months, 153 days, as the residency floor and allows temporary absences of up to twelve months for travel or work, or up to twenty-four months on an employment contract outside Canada, provided you notify the registry. Nova Scotia requires 183 days of presence, allows up to a year away if you intend to return, but makes you ineligible if you are absent more than seven months in a calendar year. Newfoundland and Labrador lets registered residents leave for up to eight months a year and, once every five years, for a full year. In every case the extension usually depends on telling the province before you go.
Employer benefits and private supplemental plans do not fill the hole. In Canada those plans exist to cover what the provincial plan leaves out, things like drugs, dental, vision and physiotherapy, and they are built around Canadian providers. They are not travel medical insurance and generally will not cover you while you are living overseas, so leaving the country tends to strip out both layers at once: the provincial plan lapses under the absence rules above, and the top-up plan does not follow you either.
Within Canada there is a safety net that has no international equivalent. Under the interprovincial reciprocal billing agreement you can usually walk into a hospital or doctor in another province and use your home health card without paying upfront. Quebec is the outlier and stays outside that agreement for physician services, so even Canadians from other provinces often have to pay a Quebec doctor and claim it back. Once you cross the national border, none of this applies: there is no card to swipe, no reciprocal billing, and, as above, your province reimburses only a token amount.
This is why even snowbirds who stay comfortably within their absence limit are advised to buy private travel insurance for every trip. The provincial coverage is still technically valid, but it pays so little abroad that it is not real protection. And when you come home for good, plan for the gap. You re-register with the provincial health authority, prove you have re-established residency, and in most provinces serve the waiting period before coverage restarts, which is exactly why bridging cover for the first weeks or months back is part of a sensible return.
Our take
For Canadians, the provincial card is close to worthless the moment you cross the border; the daily caps are rounding errors against a real hospital bill.
Treat travel medical cover as non-optional for any trip, and switch to an international plan once you are actually living abroad and your provincial coverage lapses.
Above all, make sure evacuation is covered, because neither your province nor Ottawa will pay it.
FAQ
Barely. It reimburses only small daily caps (roughly CA$75-100 a day in BC and Quebec), never pays the hospital directly, and covers no evacuation. Quebec's own example: a US$200,000 Florida stay reimbursed at about CA$300.
No. Ottawa is explicit that it will not pay your hospital bills, a medical evacuation, or an air ambulance, which alone can exceed CA$50,000.
It varies by province: roughly 212 days a year in Ontario and Alberta and 183 days in Quebec. Beyond the limit you can lose eligibility and must re-apply on return, so check your province's rule before a long trip.
Travel medical insurance for trips, with evacuation and repatriation, and an international health plan for living abroad long term once provincial coverage no longer applies. Buy it before you leave.
Only if the policy says so and you meet its stability period. A change in your condition, symptoms, or medication before the trip can void a claim, so confirm coverage in writing.
This page is the origin-country gap. It is not a passport ranking and it does not quote a premium. How we measure cost.
Find cover that actually follows you
The form asks about health and the visa. You get one offer by email. You pay the standard premium.
Get a quoteTypical destinations from here: Mexico, Portugal, Spain, Thailand and Japan. The entry rule that actually asks for cover is the Temporary Resident Visa (Residente Temporal) and the D8 Digital Nomad Residence Visa. Which product fits is the insurance choice, and whether you clear a threshold is the which nomad visa check.
Get a quote in 3 steps
- 01
Fill out
The form only asks what changes the plan.
- 02
Get a quote
We compare the panel against your route, stay and visa.
- 03
Decide on the offer
If it fits, you take the policy out with the insurer. We are not the insurer.
Have a look if this page was not the question you came with.