International health insurance for Australian digital nomads
Your home cover does not follow you abroad
Medicare pays nothing overseas except limited public-hospital cost-sharing in 11 Reciprocal Health Care Agreement countries. Evacuation is never in that deal. Australian digital nomads living abroad need international health insurance; travel cover only fits a trip that still ends.
Travel vs health once you leave
A domestic plan does not become travel insurance, and travel insurance does not become international health cover.
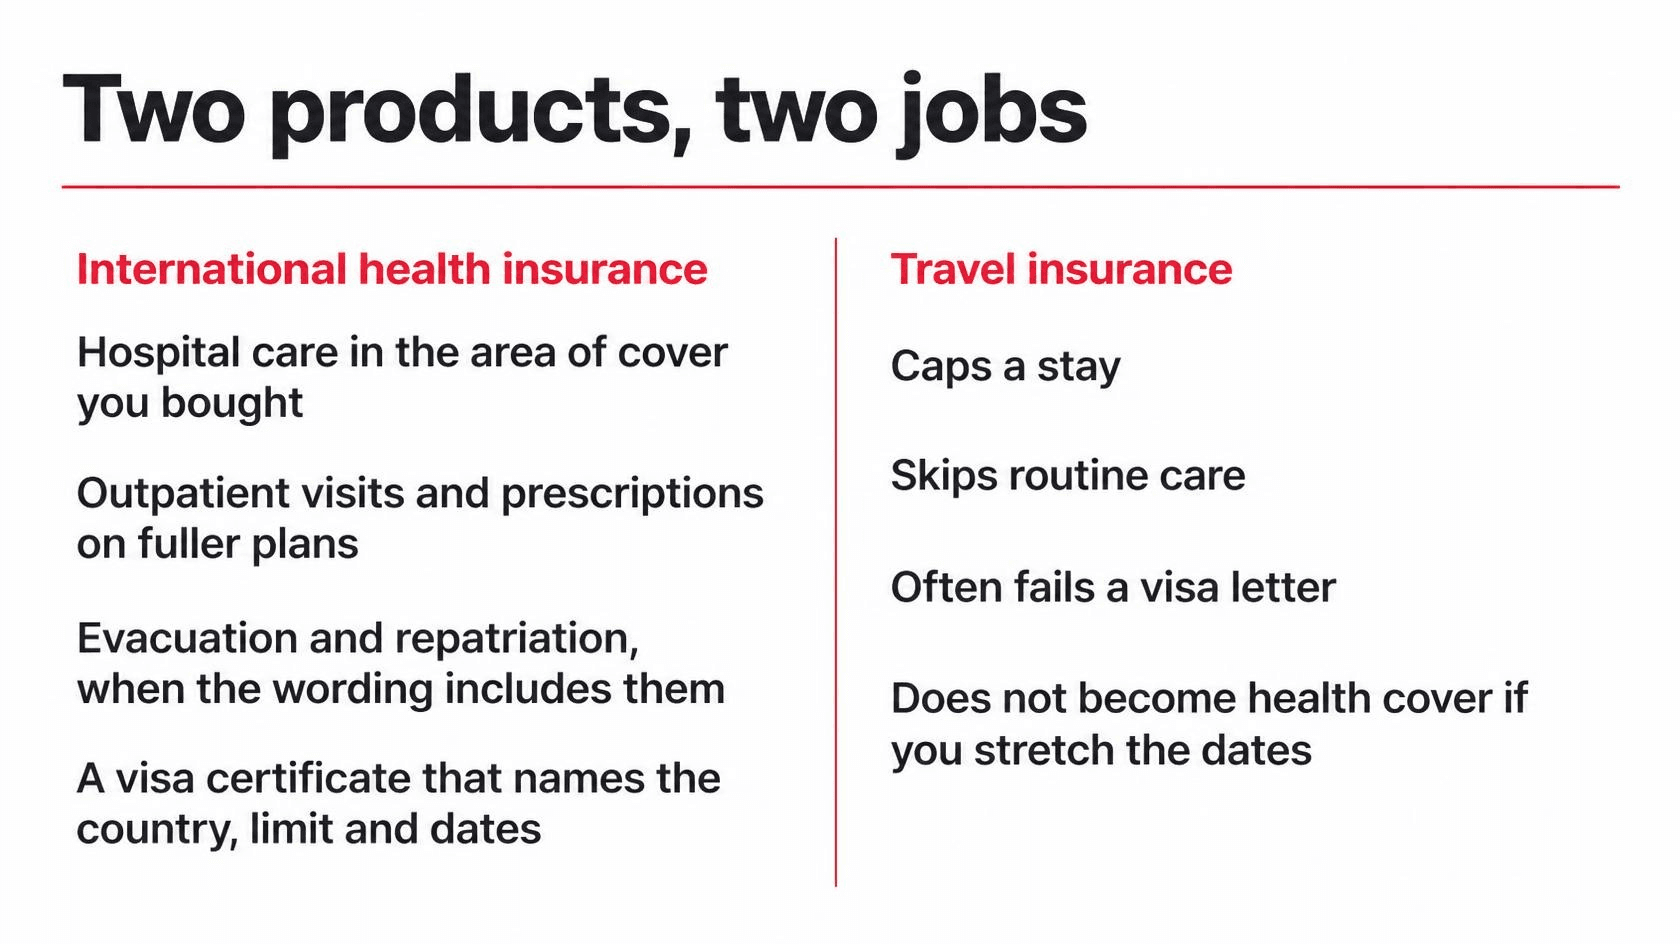
The difference is set out in our guide to travel insurance vs nomad health insurance. Use the table, then the essay below.
Travel insurance versus nomad-style cover versus international health insurance
Duration
- Travel
- Trip that ends; often 30–90 days per stay
- Nomad-style
- Continuous, renews while you are away
- International health
- Annual, portable across countries
Routine care
- Travel
- No
- Nomad-style
- Rarely
- International health
- Yes, if outpatient is in the plan
Pre-existing
- Travel
- Usually excluded
- Nomad-style
- Usually excluded
- International health
- Underwritten
Home country
- Travel
- Stops when you land
- Nomad-style
- Usually excluded
- International health
- Optional region
Visa-ready
- Travel
- Often rejected
- Nomad-style
- Sometimes
- International health
- Usually, unless a local insurer is required
Evacuation
- Travel
- If listed
- Nomad-style
- Usually
- International health
- Should be included
| Attribute | Travel | Nomad-style | International health |
|---|---|---|---|
| Duration | Trip that ends; often 30–90 days per stay | Continuous, renews while you are away | Annual, portable across countries |
| Routine care | No | Rarely | Yes, if outpatient is in the plan |
| Pre-existing | Usually excluded | Usually excluded | Underwritten |
| Home country | Stops when you land | Usually excluded | Optional region |
| Visa-ready | Often rejected | Sometimes | Usually, unless a local insurer is required |
| Evacuation | If listed | Usually | Should be included |
How long your home cover lasts abroad
Zero outside the agreement countries.
Medicare covers no overseas care at all (Health Insurance Act 1973), and the 11 Reciprocal Health Care Agreement countries only share the cost of medically necessary public-hospital care. Stay abroad more than five years and you must re-enrol in Medicare, with residency proof, before it works again on your return.
What breaks when you leave
No cover for GP or outpatient visits, no private-hospital care, no prescriptions in most cases, and crucially no medical evacuation or repatriation, which can run into the hundreds of thousands of dollars.
Outside the 11 agreement countries, even emergency public-hospital care is fully your bill. And your Australian private health policy pays nothing while you are overseas, because you suspend it before you go.
What you need instead
For trips, travel medical insurance that explicitly covers emergency treatment and medical evacuation, the two things Medicare and the agreements never do.
For living abroad longer term, an international health plan rather than a short-stay travel policy, because travel cover is built for temporary trips and neither Medicare nor your domestic private cover applies once you are resident overseas. Buy it before you leave and check it covers pre-existing conditions.
Common mistakes
- Assuming Medicare covers you overseas; it does not, anywhere outside the agreement countries
- Treating a Reciprocal Health Care Agreement as a substitute for travel insurance
- Expecting an agreement to mean full or free care; it is public-hospital essentials only
- Expecting medical evacuation or repatriation to be covered; it never is
- Thinking your domestic private health insurance travels; it is suspended while you are abroad
- Assuming Medicare is kept automatically after years away; you must re-enrol after five years overseas
- Assuming all 11 agreement countries work the same; New Zealand excludes GP and ambulance, others charge for medicines
How Australian cover really treats a leaver
Australia's Medicare pays nothing for healthcare overseas (Health Insurance Act 1973); only 11 Reciprocal Health Care Agreement countries share the cost of medically necessary public-hospital care, and none of them, nor Medicare, covers medical evacuation.
Medicare in Australia is tied to status, not to a contribution record.
The federal health department lists you as eligible if you are an Australian or New Zealand citizen, an Australian permanent resident, or someone who has applied for permanent residency. What matters for actually using it, though, is where you are. Medicare pays for treatment provided in Australia. It does not follow you overseas, which is the entire reason the reciprocal agreements below exist. Leaving to live abroad does not strip a citizen of the right to Medicare, but it does mean the card in your wallet buys you nothing while you are gone.
Australia has Reciprocal Health Care Agreements (RHCAs) with 11 countries: the United Kingdom, Ireland, New Zealand, the Netherlands, Belgium, Finland, Italy, Malta, Norway, Slovenia and Sweden. In those countries an Australian resident can use the public system for care that is medically necessary, which the agreements define as ill-health or injury that happens while you are there and needs treatment before you return home. In practice that means emergency departments, acute public hospital admissions and some outpatient care, not a full stand-in for the local system.
The limits are the point. The agreements only work in those 11 countries, so popular nomad bases like Portugal, Spain, Thailand, Mexico and Indonesia give you nothing at all. They do not cover elective or planned treatment, private-patient care in any hospital, ambulance transport, dental work or medical evacuation, and they do not cover treatment you travelled specifically to get. The 'before returning home' wording is telling. This is built for a short trip, not for someone who has actually moved, and Australia's own travel advice is clear that it is not a substitute for travel or health insurance.
While you are away, none of this reaches you outside an RHCA country, and even inside one it is emergency-grade cover only. There is no mechanism for Australia to fund your routine or ongoing care abroad. If you are settling somewhere for the long term, the expectation is that you join that country's system or carry private cover.
Coming back is the part people underestimate. Services Australia states that if you have been living overseas for more than 12 months you may need to re-enrol in Medicare rather than simply pick it back up. Because eligibility rests on citizenship or residency status, you never forfeit the right permanently, but after a long absence you re-enrol as a returning resident and have to show you are back to live, generally with your passport and residency documents. Cover is not backdated to fill the gap while that is processed, so the window between landing and completing re-enrolment is your own risk.
There is also a private-cover move that experienced nomads make. Rather than cancel Australian private hospital insurance, many suspend it. Insurers can agree to suspend cover for members who are working or studying overseas, often for up to two or three years, though the exact limit depends on the insurer. The value is continuity. Any waiting periods you have already served are put on hold and resume where they left off, so you avoid re-serving the 12-month waits for things like pre-existing conditions and pregnancy when you get back. The regulator is explicit that suspending with your insurer's agreement will not affect your Lifetime Health Cover entitlements, meaning you are treated as still holding hospital cover for those purposes. Cancelling outright throws all of that away.
Lifetime Health Cover is why that continuity matters. If you first take out hospital cover after your Lifetime Health Cover base day, you pay a 2% loading on your hospital premium for every year you are aged over 30, up to a maximum of 70%, and the loading only comes off after 10 years of continuous cover. For someone abroad, the specific rule is that no loading accumulates while you are overseas, and you are allowed a continuous overseas absence of up to 1,094 days, which is three years less a day, without it counting. Visits back to Australia of up to 90 days still count as being overseas. Go past 1,094 days without cover, though, and you pay a 2% loading when you rejoin, increasing by 2% for each further year without cover, so a multi-year nomad who simply lets a policy lapse can come home to a permanently higher premium.
Tax and the everyday extras round it out. If you become a foreign resident for tax purposes, the tax office lets you claim a full exemption from the Medicare levy for that period. But if you keep Australian tax residency while roaming, which is common for nomads who never establish a tax home elsewhere, the Medicare levy still applies, and the Medicare Levy Surcharge can hit if your income is over the threshold and you have dropped private hospital cover. That is one more reason to suspend rather than cancel. Two further things simply do not travel: the Pharmaceutical Benefits Scheme subsidises medicines dispensed in Australia on an Australian prescription, not medicines you buy abroad; and Medicare has never covered ambulances, which run on separate state and territory schemes, and RHCAs do not cover ambulance transport either.
Our take
For Australians, the agreements are a nice-to-have inside 11 countries, not a safety net.
The number that should drive your decision is evacuation, which no agreement and no Medicare benefit will ever pay and which can hit six figures.
Carry travel cover for trips and an international plan once you actually live abroad, and never let the Medicare card lull you into going bare.
FAQ
No. Medicare pays nothing for healthcare overseas. The only exception is limited public-hospital cost-sharing in the 11 Reciprocal Health Care Agreement countries, which still excludes GP visits, private care, and evacuation.
Medically necessary care in a public hospital, and some subsidised medicines, in 11 countries (including the UK, Ireland, Italy, the Netherlands and New Zealand). They do not cover GP or outpatient visits, private care, or medical evacuation.
No. It is domestic-only and is suspended while you travel, so you cannot claim on it overseas. You need separate travel or international health cover.
Not automatically. If you are overseas more than five years you must re-enrol in Medicare on return, proving Australian residency, and you have no overseas cover in the meantime.
Yes. The government is explicit that an agreement is not a substitute for insurance, mainly because evacuation and repatriation, the costliest items, are never covered.
This page is the origin-country gap. It is not a passport ranking and it does not quote a premium. How we measure cost.
Find cover that actually follows you
The form asks about health and the visa. You get one offer by email. You pay the standard premium.
Get a quoteTypical destinations from here: Bali, Thailand, Japan, Portugal and New Zealand. The entry rule that actually asks for cover is the E33G Remote Worker Visa and the Destination Thailand Visa (DTV). Which product fits is the insurance choice, and whether you clear a threshold is the which nomad visa check.
Get a quote in 3 steps
- 01
Fill out
The form only asks what changes the plan.
- 02
Get a quote
We compare the panel against your route, stay and visa.
- 03
Decide on the offer
If it fits, you take the policy out with the insurer. We are not the insurer.
Have a look if this page was not the question you came with.